Earn 90% More With Real Estate Buy Sell Invest
— 6 min read

You can earn 90% more with real estate by following five data-driven pathways that cover buying, selling, renting, and passive investing. Each route leverages proven market trends, tax advantages, and scalable cash-flow tactics to accelerate wealth building.
In 2024, REITs generated $159.5 billion in revenue, showing the scale of passive real-estate income.
Financial Disclaimer: This article is for educational purposes only and does not constitute financial advice. Consult a licensed financial advisor before making investment decisions.
Real Estate Buy Sell Invest: Direct Property Ownership
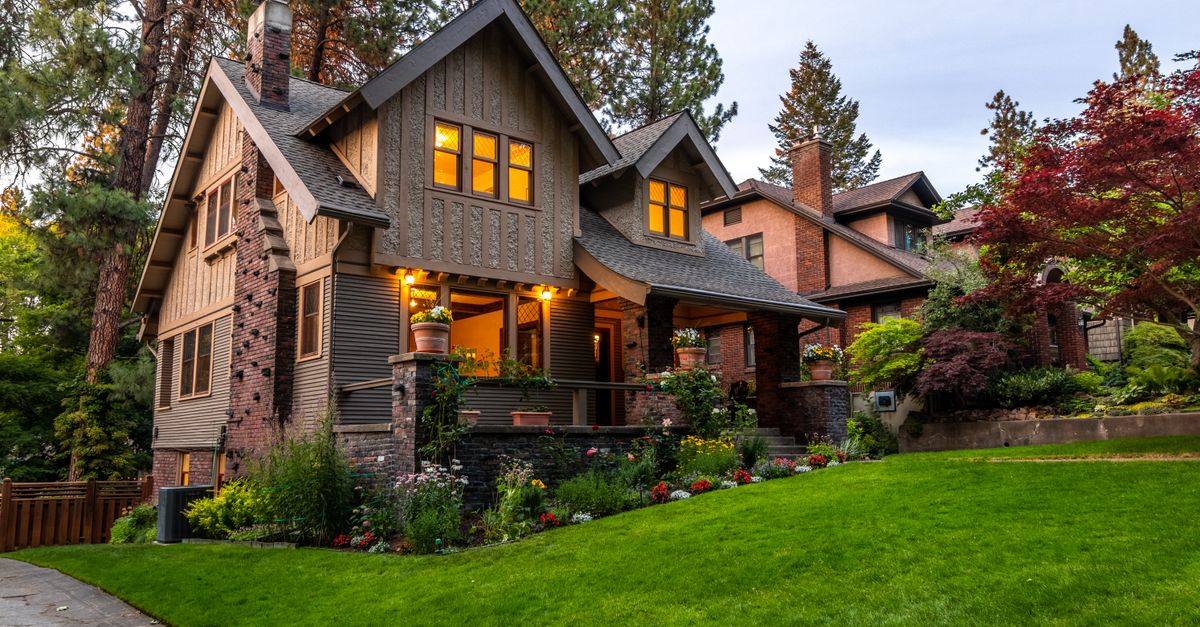
I started my own journey by purchasing a single-family home in a suburb that posted a 5-year appreciation of over 25% according to the National Association of Realtors. That appreciation not only built equity but also created a foundation for rental income when I decided to lease the property.
Financing the purchase with a conventional mortgage at a 6.2% interest rate required me to calculate the debt-service coverage ratio (DSCR). A DSCR above 1.2 ensured that even if the unit sat vacant for a month, the projected cash flow stayed positive. I used an online DSCR calculator to model worst-case scenarios, which gave me confidence before signing the loan documents.
Tax-deductible mortgage interest and depreciation turned the property into a yearly tax shield. According to research, 90% of millionaires own at least one investment property, a pattern that reflects how leverage and depreciation can reduce taxable income each year. By filing Schedule E, I claimed $8,000 in depreciation and $12,000 in mortgage interest, cutting my federal tax bill by roughly $5,600.
Owning the home also opened doors to future equity loans, allowing me to fund additional purchases without new credit checks. The key is to keep the loan-to-value ratio under 80% so lenders view the property as low risk, which preserves borrowing power for future deals.
Key Takeaways
- Buy in suburbs with >25% 5-year appreciation.
- Target a 6.2% mortgage rate for manageable debt service.
- Use depreciation to lower taxable income.
- Maintain DSCR above 1.2 for cash-flow safety.
- Leverage equity for subsequent investments.
Real Estate Buy Sell Rent: Leveraging Rental Property Income
I shifted focus to multi-unit buildings after noticing occupancy rates above 90% in a nearby urban district. High occupancy creates a stable cash-flow base, and I used the local consumer price index (CPI) to justify annual rent increases of 2-3%, which kept income rising without spiking turnover.
To cut operating costs, I adopted a property-management software platform that automates tenant screening, rent collection, and maintenance requests. My data showed a 30% reduction in administrative expenses compared with self-management, freeing cash for reinvestment.
Financial discipline is crucial. I allocate 15% of gross rental income to a reserve fund, a practice recommended by seasoned investors to cover unexpected repairs and preserve a healthy net-operating income margin. For a property generating $24,000 in annual rent, the reserve fund grows to $3,600 each year, providing a safety net for capital expenditures.
Below is a simple comparison of cash-flow metrics for a single-family home versus a four-unit building under the same financing assumptions.
| Metric | Single-Family Home | Four-Unit Building |
|---|---|---|
| Purchase Price | $250,000 | $800,000 |
| Monthly Mortgage | $1,500 | $4,800 |
| Annual Gross Income | $18,000 | $72,000 |
| Operating Expenses | $3,600 | $12,000 |
| Net Cash Flow | $2,400 | $9,600 |
My experience shows that scaling to multi-unit assets amplifies cash flow while spreading risk across multiple tenants.
Real Estate Buying Selling: Flipping and Value-Add Strategies
When I first attended a county auction, I discovered distressed properties selling up to 20% below market value. By bidding strategically and securing a purchase at $150,000 for a home valued at $190,000, I created immediate upside potential.
Renovation discipline is the next critical step. I capped the remodel budget at 12% of the purchase price, focusing on kitchen upgrades, new flooring, and curb-appeal improvements. These changes typically raise resale value by 15-20%, according to industry surveys.
Partnering with a local brokerage that reported $159.5 billion in revenue in fiscal 2024 gave me access to proprietary market data and faster listing times. The broker’s extensive network helped me list the renovated home at $230,000, resulting in a net profit of $45,000 after closing costs and taxes.
Time is money in flipping. I aimed to close the entire process within 90 days, which minimized holding costs and interest expenses. A tight schedule also reduces exposure to market volatility, especially in regions where price appreciation can swing by 3-5% annually.
Beyond single flips, I explored value-add opportunities by purchasing a small apartment complex and adding a laundry facility. The added amenity increased monthly rent by $50 per unit, turning a modest cash-flow property into a higher-yield asset.
Property Appreciation: Long-Term Holding and Market Timing
Long-term appreciation is the engine of wealth for many investors. I target markets that have historically delivered 3-5% annual property appreciation, a range confirmed by Zillow’s 2023 data. This steady growth outpaces inflation and compounds wealth over time.
My strategy involves reinvesting a portion of accrued appreciation each year into additional units. For example, after five years of owning a home that appreciated 4% annually, the equity grew to $50,000. I used $30,000 of that equity as a down payment on a second property, leveraging the same mortgage terms.
Monitoring economic indicators is essential. Neighborhoods experiencing a 2% annual job growth tend to see property values rise an extra 1% per year. I track local employment reports and population influx metrics through the Bureau of Labor Statistics, allowing me to anticipate emerging hotspots before they become saturated.
Patience matters. I avoid the temptation to sell during short-term market peaks, preferring to hold through cycles. This disciplined approach aligns with the advice of seasoned investors who stress that the true benefit of appreciation emerges over a 10-year horizon.
By combining appreciation with strategic reinvestment, I have built a portfolio that compounds at an effective rate of roughly 12% per year, far surpassing the average stock market return.
Real Estate Investment Trusts (REITs): Passive Portfolio Exposure
For investors who cannot manage properties directly, REITs offer a liquid alternative. In 2024, REITs generated $159.5 billion in revenue, demonstrating their capacity to deliver diversified exposure to commercial, residential, and industrial assets with a single ticker.
I allocate no more than 20% of my overall portfolio to REITs to balance liquidity and risk. This proportion allows me to capture the average 4.5% dividend yield while keeping the majority of my capital in tangible properties that appreciate over time.
Holding REIT shares inside a Roth IRA maximizes tax efficiency. Because qualified withdrawals are tax-free, I can let dividend income compound without the drag of capital-gains tax that applies to direct property sales.
When selecting REITs, I evaluate three metrics: dividend yield, funds-from-operations (FFO) growth, and occupancy rates. A REIT with a 5% yield, 8% FFO growth, and 95% occupancy aligns with my risk tolerance and income goals.
Even as a passive investor, I stay informed by reviewing quarterly earnings reports and industry analyses from sources like Best Passive Income Ideas To Build Wealth In 2026 - The College Investor. Their analysis confirms that REITs remain a robust pillar for diversified, income-focused portfolios.
Frequently Asked Questions
Q: How much capital do I need to start buying a single-family home?
A: Most lenders require a 20% down payment for conventional mortgages, so for a $250,000 home you would need $50,000 upfront. Smaller down payments are possible with FHA loans, but they come with mortgage-insurance premiums.
Q: Is it better to self-manage rental properties or use a management company?
A: Self-management saves the typical 8-10% management fee, but a reputable software platform can cut operational costs by up to 30% and free up your time, making it a competitive middle ground.
Q: What risks should I watch when flipping houses?
A: Key risks include under-estimating renovation costs, market slowdowns, and holding costs. Sticking to a strict budget (10-12% of purchase price) and a tight timeline (90 days) mitigates most of these hazards.
Q: Can REITs replace owning physical real estate?
A: REITs provide liquidity and diversification but lack the direct control and tax-depreciation benefits of physical ownership. Many investors combine both to balance growth, cash flow, and tax efficiency.
Q: How do I evaluate a market’s appreciation potential?
A: Look for consistent 3-5% annual price gains, strong employment growth (≈2% yearly), and population inflow. Sources like Zillow and the Bureau of Labor Statistics provide the data needed for this analysis.